📞 01375 392 087  ·  ✉ info@moyakinsurance.co.uk

Mon–Fri: 9:30am – 5:30pm

Category: Blog

  • Two Days to Comply: The £60,000-a-Worker Right-to-Work Trap Facing Every Contractor From 1 October 2026

    Two Days to Comply: The £60,000-a-Worker Right-to-Work Trap Facing Every Contractor From 1 October 2026

    Construction contractors have two days to prepare for the biggest expansion of the UK right-to-work regime since it began in 2006.

    From 1 October 2026, a contractor may face a civil penalty of up to £60,000 for each illegal worker found within a relevant subcontracting chain. This can apply even where the contractor never met the worker, did not know they were on site and had no direct contract with them.

    For a business using several subcontractors, labour-only workers, agencies or individual tradespeople, this is not a small HR issue. It is a commercial contract issue, a site management issue and an insurance issue.

    The changes are separate from the HMRC Construction Industry Scheme checks discussed recently. CIS deals with tax status, deductions and payment arrangements. The new rules concern immigration liability, right-to-work checks and the defence available if the Home Office investigates.

    What changes on 1 October 2026?

    The new extended liability rules apply where a business is contracted to provide work or services to a third party and subcontracts part of that work or services to another business.

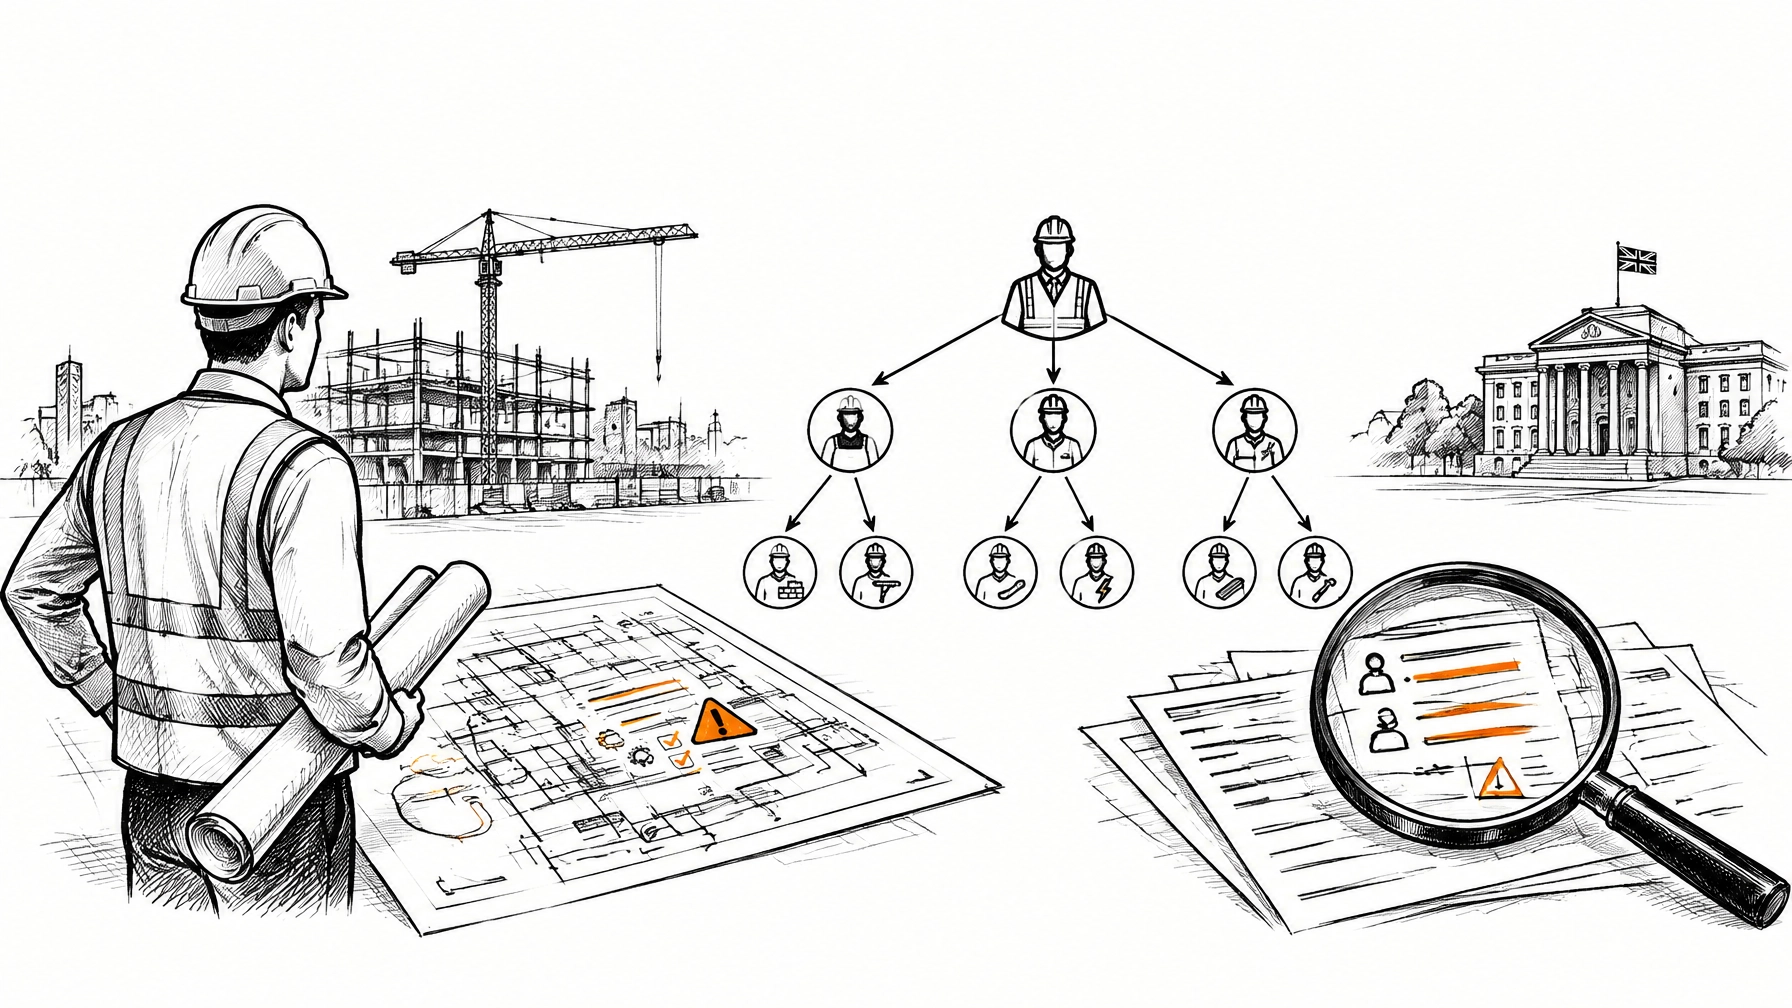
    That means liability can move up a construction supply chain. The Home Office may treat a developer, principal contractor or another business higher in the chain as the employer of a person personally carrying out work, even if that person was engaged several contractual steps below them.

    The Home Office’s construction example involves a developer contracted to build new homes. The developer engages bricklayers and groundworkers through a chain of contracts. Under the new regime, the developer may be treated as the employer of anyone working through that chain, alongside other parties above the direct relationship with the worker.

    This does not mean every party in every chain will automatically be penalised. The Home Office will decide which party or parties are liable, particularly where it is unclear who engaged the worker. It will examine the contractual structure and how the work operates in practice.

    The definition of employment is also wider. It can include:

    • Workers engaged under a worker’s contract
    • Casual and agency-style labour
    • Individual subcontractors
    • Labour-only arrangements
    • Individuals supplied through certain online matching platforms
    • Substitutes who carry out work in place of the contracted individual

    Calling somebody self-employed will not, by itself, protect a contractor. The Home Office guidance makes clear that substance matters. Who arranges the work, who supplies the individual, who controls or approves substitutions and how the arrangement operates in practice will all be relevant.

    There is an important limit. Extended liability does not apply to a client, customer or end-user at the top of the chain that is purchasing work or services for its own use rather than providing them onwards to another third party. A business buying a defined service for its own operations is not automatically caught simply because the supplier uses subcontractors.

    Branching hand-drawn subcontractor chain showing financial and regulatory exposure spreading across construction tiers

    The financial and operational consequences

    The headline figure is up to £60,000 per illegal worker. The maximum amount depends on the circumstances and previous breaches, but a five-worker breach could create a £300,000 balance-sheet event before legal costs, disruption and reputational damage are considered.

    The civil penalty itself is not insurable. This follows the settled UK position that criminal fines and regulatory penalties cannot be transferred to an insurer. Insurance cannot be used as a substitute for right-to-work compliance.

    There are also consequences beyond the civil penalty. In serious or persistent cases, criminal liability can involve an unlimited fine and up to five years’ imprisonment. Immigration officers can issue closure notices affecting premises, which could prevent work from continuing on a site. A sponsor licence may also be suspended or revoked, placing sponsored workers’ immigration status at risk.

    For contractors, a closure notice is a business interruption event even where there has been no insured physical damage. The business interruption and increased cost of working sections of a commercial combined policy may become relevant, but the response will depend on the precise policy wording, the trigger for the closure and any applicable exclusions.

    This is why it is worth reviewing more than the penalty section of your policy. A commercial combined policy may include business interruption, denial of access, legal expenses or prosecution defence elements, but those covers do not all respond in the same way and none will pay the regulatory penalty itself.

    The statutory excuse is all-or-nothing

    A contractor higher in the chain can establish a statutory excuse against extended liability, but the prescribed requirements must be met in full before the work starts.

    There are three central areas.

    1. Contractual terms

    Relevant contracts need written terms that:

    • Require the contractor or labour provider further down the chain to carry out prescribed right-to-work checks
    • Prohibit further subcontracting without prior written consent
    • Require equivalent right-to-work obligations to be passed down where consent is given
    • Give the contractor audit and inspection rights
    • Allow suspension or termination where compliance is not demonstrated
    • Require cooperation with Home Office investigations and disclosure of the supply chain

    Contract wording alone is not enough. It must reflect how the work is actually arranged and the contractor must be able to show that the controls operated in practice.

    A contractor should be able to identify the companies and individuals involved, understand who is responsible for each check and obtain reliable evidence when requested. A clause hidden in a standard subcontract will not be much help if nobody reviews whether it has been followed.

    2. Substitution controls

    Substitution clauses are a particular risk. From 1 October, if a worker can send somebody else to perform the work, that substitute must not step onto site before a prescribed right-to-work check has been completed.

    The process should identify who requested the substitution, who approved it, who checked the substitute and when the substitute was authorised to start. Site access should be blocked until those steps are complete.

    This is important for individual subcontractors who may describe themselves as operating independently. If the contract permits substitution, the engaging firm may still face extended liability if an unchecked substitute carries out the work illegally.

    3. Identity verification

    The contractor must take proportionate steps to confirm that the person on site is the same person who was checked.

    Practical controls could include site passes, access cards, attendance systems, photographic records, training records, biometric systems or digital identity checks. The right system will depend on the size of the site, the risk of substitution and the way labour is engaged.

    If a digital identity provider is used, contractors should confirm that it is registered for right-to-work checks on the Office for Digital Identities and Attributes register.

    These three areas work together. A contractor that has strong contract clauses but no control over substitutes, or good site access systems but no prescribed contractual terms, may not have a statutory excuse. Partial compliance is not a defence.

    Hand-drawn construction site entrance with an ID badge scanner, substitution arrow and check-before-start document

    What contractors should do in the next two days

    The first step is to audit every category of labour used by the business. Do not look only at PAYE employees. Include casual workers, agency labour, labour-only subcontractors, individual subcontractors, platform-sourced labour and anyone who may be sent as a substitute.

    Then map the contractual chain for each major project. Identify the client, the party responsible for delivering the work, each subcontractor and any further labour provider. Establish where the business is providing services onwards and where it is simply purchasing services for its own use.

    Commercial teams and contract managers need to be involved from the start. Your HR team cannot protect you alone from liability arising outside your own workforce. Responsibility also lies with the people drafting and negotiating commercial contracts, approving subcontractors and controlling access to sites.

    With only two days left before 1 October, contractors should:

    1. Review worker engagements and subcontracting arrangements.
    2. Take reliable immigration and commercial contract advice.
    3. Update contract templates for relevant contracts entered into from 1 October.
    4. Insert controls over further subcontracting and substitutions.
    5. Train commercial teams, site managers, procurement staff and those controlling site access.
    6. Build a check-before-start workflow for every permitted substitute.
    7. Link site access to an identified individual and completed checks.
    8. Confirm any digital identity provider is registered for the correct right-to-work service.
    9. Keep copies of contracts, checks, audits, approvals and decisions.
    10. Make sure the business can produce evidence quickly if the Home Office asks for it.

    The Home Office guidance is available in its draft employer’s guide to right-to-work checks. Contractors should also consider the practical warnings reported by Construction News.

    How this affects construction insurance

    The right-to-work failure itself is not an insurable penalty, but it can affect the wider risk profile of the business.

    Underwriters look at how a contractor sources labour, manages subcontractors and demonstrates competence. A business that cannot evidence who is working on its sites, how subcontractors are checked or how substitutions are controlled may look like an uncontrolled employers’ liability and public liability risk.

    Public liability policies commonly require the insured to take reasonable precautions and comply with relevant safety procedures. If an incident involves a worker who should not have been on site, the absence of identity and right-to-work controls could become relevant when the insurer considers whether reasonable precautions were taken. This does not mean every claim will automatically be declined, but it can create a serious coverage and claims-handling issue.

    Employers’ liability and public liability exposure also depends on how labour is classified and controlled. Labour-only and self-employed subcontractor arrangements have always needed careful review. The new regime brings immigration exposure into the same conversation. A single due-diligence process should cover status, competence, insurance, right to work and site access.

    Legal expenses and directors’ and officers’ insurance also deserve attention. Criminal investigation and prosecution defence costs, legal representation at interviews and regulatory response costs may be available under separate sections, but they are frequently absent or limited. The policy will not pay the penalty itself.

    The Commercial Court’s September 2026 decision in Liberty Managing Agency v Chedid also provides a useful reminder that properly worded D&O policies can protect defence costs while allegations remain unproven. Where the policy requires fraud to be established by a final decision or formal admission before avoidance or an exclusion can be relied upon, defence costs may need to continue to be advanced until that threshold is met. The precise wording remains critical.

    Hand-drawn commercial insurance folder beside a construction site, business interruption clock, legal scales and protective shield

    Act with only two days left before 1 October

    This is a different risk from the recent HMRC CIS changes, but the practical lesson is similar. Labels and assurances are not enough. Contractors need to understand how labour is really engaged, how the subcontract chain is built and what evidence exists when something goes wrong.

    At Moyak, our Individual Approach and Care About Every Client means we start with how your business actually operates. A main contractor managing a 40-firm supply chain does not have the same exposure as a small firm with a direct workforce and two regular subcontractors.

    As a Business Insurance Broker in Essex, Kent and London, we work with the UK’s leading master insurance brokers to help clients obtain suitable cover for their budget and property, often saving them a fortune on small business insurance quotes. Our general contractor insurance service is designed around the real structure of your business rather than a generic description of your trade.

    Bring us your subcontractor list, contract templates and current liability and employers’ liability schedules. We will help you identify where the real exposure sits and whether your insurance arrangements reflect it.

    There are now only two days left before 1 October 2026. This article is general information and is not advice on any specific contract, worker or insurance policy. Specialist immigration and employment advice should be taken where required. To discuss your arrangements, contact Moyak Insurance Services.
  • A £1.15m Month: 5 Things Every Contractor Must Know About HSE Fines, Employers’ Liability and What Insurance Actually Pays

    A £1.15m Month: 5 Things Every Contractor Must Know About HSE Fines, Employers’ Liability and What Insurance Actually Pays

    September 2026 has been an unusually heavy month for Health and Safety Executive enforcement in construction. On 9 September, Appledorn Developments and T Vaughan Limited were fined £500,000 and £650,000 respectively after the death of Gheorghita Arsene in a trench collapse at Banstead in 2020. T Vaughan was also ordered to pay £40,000 in costs, taking the wider financial penalty close to £1.2 million.

    Mr Arsene’s death was described by the HSE as preventable. The trench had no supports and excavated soil had been placed immediately beside it, despite the well-known risks associated with excavation work. The company’s contracts manager, Anthony O’Connor, also received a suspended custodial sentence and unpaid work order.

    That was not an isolated enforcement action. A roofing boss in St Cyrus was fined £15,000 after a worker fell to his death, while Hillbeck Homes was fined £300,000 plus £9,284.05 in costs after Joseph Tuck, a temporary labourer in only his second week, fell through an unprotected stairwell opening and suffered serious spinal injuries.

    The important insurance point is often missed when cases like these make the news. A serious incident creates several separate financial consequences, and they do not move together. The criminal fine, the civil compensation claim, the cost of defending the business and the effect on future insurance and tenders are different issues.

    For contractors reviewing their Construction Contractor Insurance, these are the five points that matter.

    1. The criminal fine is not insured

    There is no insurance policy that transfers an HSE criminal fine to an insurer.

    That is not a matter of finding the right endorsement or negotiating a more comprehensive General Contractor Liability Insurance package. It is a matter of public policy and settled insurance law. A criminal fine imposed because a business has breached health and safety law is intended to punish and deter that business. Allowing the company to pass the fine to an insurer would undermine that purpose.

    The £1.15 million in fines imposed on Appledorn and T Vaughan therefore sits with the businesses themselves. It is a balance-sheet event, not an insured loss. The same principle applies to personal fines imposed on directors, managers or other individuals. A company policy cannot insure a person against a criminal fine or a custodial sentence.

    This distinction is one of the most common misunderstandings we see when speaking to contractors. A business may have £10 million of employers’ liability cover, a commercial combined policy and a separate liability programme, but none of those covers the criminal penalty itself.

    Legal expenses or defence costs can be a different question. Depending on the wording, separate legal expenses, directors’ and officers’ or corporate protection cover may assist with legal representation and certain investigation costs. That does not mean it pays the fine. Contractors need to check the policy wording carefully rather than assume that every cost connected with a prosecution is covered.

    HSE prosecutions are also public record. That matters beyond the immediate fine. Tendering clients may consider enforcement history when deciding whether to award work, and insurers may take the conviction into account when assessing the business at renewal. The public record can influence the future cost and availability of cover even when no civil claim is ultimately made.

    Split illustration showing an uninsurable criminal fine on one side and employers’ liability protection on the other

    2. Employers’ liability is where the civil claim works

    The criminal prosecution and the civil compensation claim are separate legal processes. They involve different tests, may be dealt with in different courts and can reach different outcomes.

    Employers’ liability insurance exists to respond to compensation claims when an employee is injured or becomes ill because of their work. In Great Britain, most employers must hold EL cover as soon as they become an employer. The legal minimum is £5 million from an authorised insurer, although £10 million is standard in many commercial policies. The government’s Employers’ liability insurance guidance explains the basic requirements and penalties for failing to arrange cover.

    The policy is intended to fund compensation and associated legal costs, not to pay an HSE punishment. If a worker is killed or seriously injured, the family’s civil claim may include loss of financial support, bereavement-related damages and other recognised heads of compensation. The value of that claim is assessed separately from any criminal fine.

    The Appledorn case shows why historic records matter. Appledorn entered liquidation in 2023, before the criminal trial concluded. If a bereaved family were left to pursue only the company, there might be no meaningful assets available from which to recover compensation. Where valid employers’ liability insurance was in force at the time of employment, the historic insurer may still be identified and the claim pursued under the applicable rights against insurers process.

    This is where the Employers’ Liability Tracing Office is particularly important. ELTO maintains a central database containing more than 40 million employers’ liability policy records spanning over a century. It exists to help claimants and their representatives identify the insurer that covered an employer during the relevant period, including where the employer has since dissolved, merged or ceased trading.

    For contractors, the practical lesson is straightforward. Keep policy schedules, certificates, insurer details and policy years traceable from day one. If a claim arises years after a company has stopped trading, the record of who insured the business during the exposure period may be more important than the company’s current financial position.

    3. The conviction changes the business’s future insurability

    A serious incident does not end when the court imposes a fine.

    A conviction becomes part of the company’s risk history. Future insurers will want to understand what happened, why it happened and what has changed. Clients awarding contracts may ask similar questions, particularly where the contractor is bidding for work involving excavations, demolition, roofing, structural alterations or work at height.

    For T Vaughan, which remains trading and has been given six years to pay its fine, the conviction is now part of its commercial record. The company will need to demonstrate that its systems are not simply documented but implemented and monitored in practice.

    The same applies to individuals. Directors, contracts managers and site supervisors can face personal prosecution where their acts or omissions contribute to an incident. Personal fines and custodial sentences are not insured by the company. A business should therefore consider whether it has suitable legal representation and investigation cover, while making sure managers understand their own responsibilities.

    This is also where underwriters look beyond the certificate. They may ask about previous notices, prosecutions, claims, near misses, staff competence, subcontractor controls and the way safety responsibilities are allocated. A clean claims history is not enough if the management system appears weak.

    4. Employers’ liability is compulsory, but the policy still needs checking

    Having EL insurance does not automatically mean the business has the right protection.

    Start with the limit. £5 million is the statutory minimum, but £10 million is common and a higher limit may be appropriate for contractors with larger workforces, multiple sites or a greater potential for catastrophic injury. The right limit depends on the actual business rather than a standard market assumption.

    Check the named entities as well. Group companies, subsidiary businesses and separate trading names must be correctly included. It is surprisingly easy for a contractor to restructure, add a new company or change its trading arrangements without updating the policy.

    Subcontractor arrangements need careful attention too. A genuine subcontractor may have their own liability arrangements, but labour-only subcontractors can be treated differently and may fall within your employers’ liability exposure. Do not rely solely on a certificate handed over at the start of a project. Check what the subcontractor is doing, who controls the work and whether their insurance remains current.

    Other points worth reviewing include:

    • The excess and whether the business could afford it following a serious incident.
    • Claims notification requirements and what must be done immediately after an accident.
    • The treatment of occupational disease and long-tail claims, including HAVS, asbestos, silica and noise-induced hearing loss.
    • Whether all employees, temporary workers and relevant labour-only subcontractors are dealt with correctly.
    • Whether legal costs, inquests and prosecution representation are covered or require separate insurance.

    Many contractors assume their commercial combined policy or General Contractor Liability Insurance responds to everything connected with an incident. It does not. EL may respond to an employee’s civil compensation claim, while public liability may apply to injury to a third party. The criminal fine remains uninsured, and investigation or representation costs may sit under a separate section or separate policy.

    The risk is not only an inadequate sum insured. It can also be the wrong entity, the wrong classification of worker or a gap in the policy wording.

    Historic insurance certificates, filing cabinet and family connected to a construction company, representing ELTO policy tracing

    5. The management system is the real risk control

    Insurers price the risk presented by the business, not the quality of its paperwork alone.

    The Hillbeck Homes case is a clear example. Securing the stairwell cover or installing suitable edge protection would have prevented the fall. The Banstead trench case carries the same practical message. Proper support and spoil management were basic precautions for a known excavation risk.

    For most contractors, the most useful controls are not complicated:

    • Use task-specific risk assessments for work at height, excavations and groundworks.
    • Install physical safeguards, including guardrails, secured coverings, scaffolding and edge protection.
    • Make sure the safeguards are checked after changes to the site.
    • Provide supervision proportionate to the work and the experience of the people carrying it out.
    • Record near misses and act on them rather than treating them as paperwork.
    • Make sure subcontractor responsibilities are understood and monitored.

    This is particularly important for groundworks, demolition and work-at-height contractors. Underwriters will often scrutinise these areas at renewal because the potential severity is high and the basic controls are well established.

    A strong system also helps defend a civil claim. The risk assessment is not a substitute for safe work, but records showing how the work was planned, supervised and reviewed can be important evidence. More importantly, a management system that is followed on site is what prevents the incident in the first place.

    What contractors should do now

    The September enforcement cases are a reminder that fines and insurance run on separate tracks. EL cover can be vital when an injured worker or bereaved family seeks compensation, but it cannot pay the criminal penalty. The business must also consider its reputation, tendering position, future underwriting and the personal exposure of managers.

    At Moyak Insurance Services, our individual approach means we look at how your business actually operates. We ask what trades you undertake, how many people and subcontractors are on site, which entities are involved and where the serious risks sit. Employers’ liability and liability cover for a groundworks contractor should not be structured in the same way as cover for a fit-out firm.

    As a Business Insurance Broker in Essex, Kent and London, we work with leading UK master insurance brokers to help secure suitable cover for your budget and property, often saving small businesses a considerable amount on their insurance quotes.

    Bring us your current EL schedule, policy wording and subcontractor arrangements. We can check the named entities, limits, worker classifications, notification requirements and the gaps between employers’ liability, public liability, legal expenses and other covers.

    For official guidance, see the HSE employers’ liability publication, the HSE’s work at height guidance and the HSE report on the Banstead trench prosecution.

    This article provides general information only. It is not advice on a specific incident, claim, prosecution or insurance policy.

  • £20m Gone, Nothing Recovered: 5 Insurance Checks the Torsion Collapse Demands of Every Contractor

    £20m Gone, Nothing Recovered: 5 Insurance Checks the Torsion Collapse Demands of Every Contractor

    Torsion Construction entered administration on 29 July 2026. The Leeds contractor, which worked across student accommodation and build-to-rent projects, had grown turnover from £57m in 2023 to £165.4m in 2025, with around 115 employees.

    Then the position changed sharply.

    In its 2026 trading period, Torsion recorded a loss of £847,000 on turnover of £78m, compared with a pre-tax profit of £497,000 on £165m in the previous year. Rising costs, a slower market and site-specific overspend and delay all contributed to the pressure.

    The administrators, James Clark and Howard Smith of Interpath, have reported approximately £20m owed to unsecured creditors, including around £15.7m to trade creditors. Hundreds of suppliers are understood to be affected, and the administrators say unsecured creditors are highly unlikely to receive anything.

    That is the part every contractor and subcontractor should consider carefully. This is not primarily a story about a failed contract clause or a missed compliance obligation. It is about what happens when the customer who owes you money can no longer pay.

    The dominoes are still falling. Torsion Developments entered receivership in September, and on 21 September 2026, Torsion Projects filed a notice of intention to appoint an administrator. Torsion Projects had reported turnover of £47m and a pre-tax profit of £505,000 for 2024, and specialised in care homes, retirement living and residential work, much of it for sister company Torsion Care.

    For contractors reviewing their construction contractor insurance, there are five practical checks to make now.

    1. Do you have trade credit insurance?

    Most contractors understand public liability, employers’ liability and contract works insurance. Far fewer have trade credit insurance.

    That matters because trade credit insurance is designed to respond when a business customer fails to pay because of insolvency or prolonged default. For a subcontractor, the customer may be the main contractor. For a main contractor, it may be the developer or employer.

    A £15.7m trade creditor pool with little or no expected recovery is exactly the type of loss this form of cover is intended to address. It is not a replacement for liability insurance, and it does not pay for defective workmanship or poor project performance. It protects the receivable, subject to the policy terms.

    When reviewing a policy, ask:

    • Is the cover written on a whole-turnover basis or only for named buyers?
    • Is the contractor or developer you are working for approved by the insurer?
    • What credit limit has been set for that buyer?
    • Are you already above the approved limit because of unpaid applications, retentions or variations?
    • What is the maximum extension period for overdue debt, commonly 90, 120 or 180 days?
    • What are the deadlines for notifying overdue invoices, adverse information and insolvency?
    • What excess applies?
    • Are retentions, certified sums, agreed variations and applications for payment included?

    The important point is that trade credit cover is not automatic simply because you have bought a policy. If the debtor is not approved, the credit limit is too low, or notification conditions are missed, the expected protection may not be available.

    Construction-specific wordings can sometimes address exposure beyond ordinary invoices, including work completed, applications, variations and retention balances. But those items must be agreed and documented. Never assume they are covered because the schedule says “trade credit”.

    Hand-drawn illustration of a subcontractor reviewing an order book, invoices and an insurance shield

    2. Remember that retentions are not held in trust

    A 5% retention can look manageable when viewed against one project. Across several sites, it becomes a material loan to the main contractor.

    At present, retention money is not generally required to be held in trust for subcontractors. If the contractor becomes insolvent, the retention can sit in the same unsecured creditor pool as unpaid invoices. You may have completed the work, released labour and materials, and met every obligation, yet still lose the money held back.

    That is why I think contractors should stop treating retentions as a safety net. In practice, they are often an unsecured loan to the payer.

    Possible alternatives include:

    • Retention bonds
    • Retention replacement guarantees
    • Retention insurance
    • Construction-specific trade credit insurance that expressly includes retention balances

    The proposed Commercial Payments Bill is intended to prohibit the deduction and withholding of retentions in construction contracts. It also proposes maximum payment terms of 60 days and mandatory interest at 8% above the Bank of England base rate for late payments. However, the legislation is not yet in force and the timing for the retention measures remains subject to consultation and transition arrangements.

    In practical terms, contractors cannot wait until around 2030 and hope the law solves today’s cash-flow exposure. Review your existing retentions now, identify where the balances sit and ask what would happen if each payer entered administration tomorrow.

    3. Establish whose insurance responds if the project stops

    If a main contractor fails halfway through a project, the immediate problem is not only unpaid money. There may be completed works, materials on site, unfixed materials, hired plant and temporary works exposed to damage, theft or weather.

    This is where the distinction between contract works insurance and trade credit insurance becomes important.

    Contract works or contractors’ all risks cover generally responds to physical loss or damage to the works. It does not pay you simply because a customer owes you money. A project can be perfectly undamaged but still leave you with a substantial unpaid application.

    Check whether the project is insured under:

    • Your own contract works policy
    • The employer’s arrangement
    • A joint names policy
    • A project-specific policy with particular endorsements

    If the arrangement is based on the employer insuring the works, sometimes described through a DE4-style structure, confirm what happens if that employer or developer enters administration. Do not rely only on a statement that your interest is noted. Ask for the actual policy position.

    You should also establish:

    • Whether materials on site and unfixed materials are insured
    • Who covers your plant and hired-in plant
    • Whether the policy remains effective after the employer’s insolvency
    • Who has authority to access and secure the site
    • Whether you can recover your materials, equipment and temporary works
    • Whether your subcontract gives you a right to enter the site

    A joint names arrangement can protect the physical works, but it does not guarantee payment of your contract sum. That is a separate financial risk.

    4. Test cash flow, payment terms and your own insurance arrangements

    The latest Payapps research surveyed 127 UK subcontractor professionals and gives a useful picture of the pressure in the payment chain.

    It found that:

    • 79% wait longer than they should to be paid
    • 73% experience payment process disputes
    • 29% have avoided working with a contractor because its payment process was too difficult
    • 84% say a contractor’s payment reputation affects whether they bid or price future work
    • 68% have increased rates or added a risk margin because of slow or unreliable payments

    This is not just an administrative inconvenience. It affects pricing, capacity, borrowing and insurance.

    Before bidding for work, credit-check the main contractor or developer. Use credit reports and early warning services such as Red Flag Alert-style monitoring. Check County Court Judgments, insolvency applications and changes in filing behaviour. Set an internal exposure limit for each customer rather than allowing one apparently successful relationship to absorb an ever-growing balance.

    Do not rely on “we have worked with them for years”. Torsion’s growth and previous trading performance did not prevent a rapid reversal when lending was withdrawn, invoice discounting support was removed and approximately £6m of additional funding could not be raised.

    You should also review your own insurance payment arrangements. If premiums are funded by instalments, a bad debt month can put those payments under pressure. An unpaid invoice may also reduce turnover, change your exposure profile and affect renewal discussions.

    Document overdue invoices promptly and follow the notification requirements under any trade credit policy. The same discipline applies to applications, certificates, variations, retention records and correspondence.

    5. Review group company and related-party exposure

    Torsion shows why checking one company name is not enough.

    Torsion Construction’s administration was followed by receivership action involving Torsion Developments and now an administration notice from Torsion Projects. The companies may be legally separate, but their commercial relationships, projects, funders and cash flows can still be closely connected.

    Before accepting work from a group, ask:

    • Which company is actually signing the contract?
    • Is that the trading company, the asset-owning company or a project company?
    • Is there a parent company guarantee?
    • Does the guarantee come from a company with real assets?
    • Are payment obligations supported by a funder or only by another group entity?
    • Are intercompany balances genuinely recoverable?

    In Torsion’s case, approximately £15.7m was reportedly owed to the business by related companies, and administrators are pursuing those balances. That figure is a reminder that money moving around a group is not necessarily money available to pay subcontractors.

    Direct payment arrangements can also complicate matters. Torsion’s directors arranged for development funders to pay some subcontractors directly, which protected certain supply chain payments but reduced the company’s working capital. If you agree to direct payment, record who is contractually responsible, which debt is being discharged and who carries the insurance obligations.

    Your general contractor liability insurance is not designed to absorb a customer’s bad debt. Consider how it should sit alongside commercial combined protection, trade credit insurance and legal expenses cover for contract disputes, adjudication and debt recovery. The exact response depends on the wording, so it needs to be reviewed rather than assumed.

    The paperwork can change the outcome

    The Torsion position is serious, but it is not proof that every insolvency produces the same result. Reporting around Jerram Falkus suggests that subcontractors may receive a partial payout, depending on asset recoveries and the administrators’ assessment.

    That contrast matters. The paperwork you hold can affect whether your claim is recognised, whether you can prove the amount owed and whether another route to recovery exists. Keep signed contracts, payment applications, certificates, variations, retention schedules, notices and correspondence together and accessible.

    For contractors in Essex, Kent and London, the wider lesson is straightforward. We regularly see businesses with strong liability insurance but no protection if the customer stops paying. That is one of the most common gaps in an otherwise respectable insurance programme.

    At Moyak Insurance Services, our approach is individual because every order book and supply chain is different. We care about every client, and we work with the UK’s leading master insurance brokers to find suitable protection for the risk and budget, often helping small businesses secure better value than they expect.

    Bring us your order book and payment terms. We can look at where the real exposure sits, which customers create concentration risk and whether your current business insurance responds to the risks you actually face.

    This article provides general information only. It is not advice on a specific contract, insolvency, insurance policy or claim. Contractors should obtain appropriate legal, financial and insurance advice before making decisions.

    Sources: Interpath and Torsion creditor reporting, Torsion Projects administration notice, Companies House filings for Torsion Developments, Payapps subcontractor payment research and the Government’s Commercial Payments Bill overview.

  • Signing a JCT Contract? 5 Insurance Clauses That Can Leave Your Cover Void (2026 Guide)

    Signing a JCT Contract? 5 Insurance Clauses That Can Leave Your Cover Void (2026 Guide)

    Signing a JCT contract is usually seen as a positive step. The project is agreed, the price has been negotiated and work can finally be scheduled. But the insurance wording deserves just as much attention as the scope of works.

    The problem I see in practice is not always that a contractor has no insurance. More often, they have a policy that looks suitable but does not respond in the way the contract requires. The result can be a breach of contract, a disputed claim, an unexpected excess or a serious funding gap when something goes wrong.

    That is why the key question is not simply, “Whose policy is it?” The more important question is, “Does the policy actually provide the cover required by the JCT contract?”

    Recent JCT insurance guidance from Paterson Insurance Brokers and Allianz’s refreshed construction capability for cross-border EEA work have both brought contract alignment back into focus. For contractors taking on work in Essex, Kent, London or elsewhere in the UK, these are the five checks I recommend completing before signing.

    1. Confirm who insures the works

    The first check is responsibility. The contract particulars and insurance schedule should make clear whether the contractor or employer arranges the contract works insurance.

    In the schedule, you may see DE3 used to indicate that the contractor arranges the contract works insurance, while DE4 may indicate that the employer arranges it. However, the terminology and clause numbering can vary between JCT forms, so do not rely on the abbreviation alone. Read the full insurance option and confirm the arrangement with your broker and solicitor.

    The wider JCT structure is generally understood as follows:

    • Option A: commonly used for new builds, with the contractor arranging Joint Names All Risks insurance for the works.
    • Option B: also associated with new builds, but with the employer arranging the works insurance.
    • Option C: commonly used for alterations, extensions and work to existing structures, with the employer arranging cover for the existing structure and the new works in Joint Names.

    This distinction matters because a contractor may price a project believing the employer is insuring the works, while the signed contract places the responsibility on the contractor. If the contractor then relies on an annual policy that does not meet the JCT requirements, the project may start without compliant protection.

    For a new build under Option A, the contract works policy will typically need to cover the project on a Joint Names All Risks basis. For refurbishment or extension work under Option C, the employer may be responsible for insuring both the existing building and the new works.

    Do not assume that an existing commercial or household buildings policy automatically continues once major works begin. The construction activity must usually be declared and accepted by the property insurer.

    Construction insurance responsibility paths for contractor, employer and existing structures

    2. Check that “Joint Names” really means Joint Names

    A frequent misunderstanding is the difference between a party being named as an insured and having its interest merely noted on a policy.

    A JCT contract may require the employer and contractor to be insured in Joint Names. This normally gives both parties direct rights under the policy and helps prevent the insurer from pursuing one insured party to recover a claim payment made to the other. That recovery process is known as subrogation.

    By contrast, a policy that only says “principal’s interest noted” may not give the contractor the same protection. The employer may be recognised as having an interest in the project, but that does not necessarily make them a full insured party with the rights required by the contract.

    This is one of those details that can look satisfactory on a certificate but fail when the policy wording is examined closely.

    Before signing, ask your broker to obtain written confirmation of:

    • The exact names shown on the policy.
    • Whether both parties are insured in Joint Names.
    • Whether a waiver of subrogation applies.
    • Whether the policy includes any non-vitiation wording.
    • Whether the arrangement applies to the full period required by the contract.

    The correct endorsements may need to be negotiated with the insurer. A standard certificate of insurance is not always enough evidence that the JCT obligation has been met.

    3. Do not overlook existing structures

    Existing structures create a different risk from a new building. The contract price may be £500,000, but the building being altered could be worth several million pounds. If the existing structure is not insured correctly, the financial exposure can be far greater than the value of the works themselves.

    This is especially important under Option C arrangements. The employer’s property policy may be intended to insure the existing building and the new works, but only if the works have been declared and the insurer has endorsed the policy.

    A standard buildings policy may restrict or exclude:

    • Structural alterations.
    • Underpinning and excavation.
    • Basement construction.
    • Major roof works.
    • Work involving heat or temporary openings.
    • Damage caused by contractors.
    • Unoccupied or partially occupied premises.

    Contractors should ask for evidence that the employer’s insurer has accepted the project. It is not enough to hear that “the building is already insured”. The insurer needs to know what is happening, when it will happen and how the work affects the existing structure.

    Contract works policies can also restrict cover for existing structures. Some policies cover only the new works, while others may offer existing structures cover subject to a separate declared value, survey information and specific conditions.

    This is where a broker’s individual approach is valuable. The correct question is not simply whether there is a policy in place, but whether the policy reflects the building, the work and the contract.

    4. Treat JCT Clause 6.5.1 cover as a separate workstream

    Public liability insurance is not the same as JCT Clause 6.5.1 non-negligence insurance.

    Public liability generally responds where the contractor is legally liable for injury or property damage, often because negligence has been established. Clause 6.5.1 cover is intended to address certain damage to neighbouring property even where negligence cannot be proved.

    The risks can include damage arising from:

    • Underpinning.
    • Piling.
    • Excavation.
    • Vibration.
    • Subsidence or heave.
    • Weakening or removal of support.
    • Lowering of groundwater.
    • Collapse or other specified structural effects.

    For example, a neighbouring building could develop serious cracking after piling works, even though the contractor followed the method statement and acted with reasonable care. Public liability may not respond if there is no negligence. The JCT non-negligence insurance is designed for that different exposure.

    This cover is frequently unavailable for higher-risk projects or is offered only with strict conditions, sub-limits and significant excesses. It may also exclude damage to the contract works themselves, which is another reason not to treat it as a replacement for contract works insurance.

    The cover may be arranged as a separate policy or as an extension, depending on the insurer and project. The contract may also require it to be in Joint Names and may specify a minimum limit.

    Do not leave this discussion until the week before work starts. Insurers may require site information, structural details, neighbouring property surveys and method statements before terms can be considered. If the project involves piling, basement excavation or work close to older buildings, the insurance conversation should begin during contract negotiation.

    Non-negligent insurance protection for neighbouring buildings beside a construction site

    5. Align sums insured, exclusions and the policy period

    Even when the right type of policy has been arranged, the limits and conditions may still be wrong.

    For contract works, the sum insured should generally reflect the full reinstatement value rather than simply the contract price. It may need to include:

    • Materials and labour.
    • Professional fees.
    • Debris removal.
    • Inflation during the construction period.
    • Additional costs associated with rebuilding.
    • The value of temporary works where relevant.

    For existing structures, the declared value should reflect the cost of rebuilding the building, not its market value. Underinsurance at this stage can create a major problem after a fire, flood or structural loss.

    Check the liability limits as well. JCT contracts commonly require public liability of £5 million or £10 million, but the amount in your policy must match the contract. If the contractor has design responsibility, professional indemnity insurance may also be required, sometimes for six or twelve years after completion.

    The exclusions deserve equal attention. Ask specifically about:

    • Defective workmanship.
    • Defective design.
    • Wear and tear.
    • Gradual deterioration.
    • Pollution.
    • Flood.
    • Ground conditions.
    • Damage to the defective part itself.
    • Damage to existing structures.
    • High-risk postcodes or known subsidence areas.

    The policy period must also run from the required commencement date through the construction period and any maintenance or defects period specified in the contract. A policy that expires at practical completion may not satisfy the full contractual obligation.

    Why contract alignment matters more than the policy label

    Terms such as “contractors all risks”, “general contractor liability insurance” and “construction insurance” are useful starting points, but they do not prove that the cover is suitable for a particular JCT contract.

    Two contractors can hold policies with similar names but very different endorsements, exclusions and limits. One may be able to add an employer in Joint Names, while another may only note their interest. One may provide Clause 6.5.1 cover, while another excludes the relevant risks completely.

    That is why we recommend sending the insurance schedule to your broker before signing the contract. At Moyak Insurance Services, we take time to understand how the business actually operates, what work is being carried out and which party has accepted each risk.

    As an independent general contractor insurance broker, we work with leading master brokers and insurers to help businesses secure suitable cover for their projects and budgets. We can also review wider commercial combined insurance where your business needs property, liability, business interruption and related protection alongside construction cover.

    For contractors and developers across Essex, Kent and London, our role is not just to provide a certificate. It is to identify where the contract and policy do not match, explain the practical consequences and help obtain the endorsements needed before work begins.

    Final checklist before signing

    Before signing a JCT contract, confirm:

    1. The exact insurance option and responsible party.
    2. Whether the works must be insured in Joint Names.
    3. Whether existing structures are included and properly declared.
    4. Whether Clause 6.5.1 non-negligence cover is required.
    5. The required limits, sums insured, excesses and policy period.
    6. Any design, defective work, flood, pollution or ground condition exclusions.
    7. That the policy evidence matches the contract particulars.

    The biggest cause of insurance disputes is often not whose policy it is. It is the gap between what the contract requires and what the policy actually provides.

    Bring your broker into the conversation before the JCT contract is signed, not after a loss has exposed the mismatch. If you are arranging Construction Contractor Insurance or reviewing business insurance in Essex, Kent or London, contact Moyak Insurance Services for a practical, individual review built around your project and your business.

    This article is for general information and does not replace advice on the specific JCT form, contract particulars or insurance policy wording. The relevant contract and policy should be reviewed by your solicitor and insurance broker before signing.

    Sources and further reading

  • HMRC Is Coming for Your Subcontractor Chain: 5 Checks Every Contractor Must Make Before the Next CIS Audit (2026 Rules)

    HMRC Is Coming for Your Subcontractor Chain: 5 Checks Every Contractor Must Make Before the Next CIS Audit (2026 Rules)

    The Construction Industry Scheme has always required contractors to verify subcontractors, apply the correct deductions and submit accurate returns. Since 6 April 2026, however, the risk has moved further up the chain.

    Under HMRC’s new CIS fraud regime, a principal contractor can be pursued where it knew or should have known that payments or CIS credits were connected to deliberate non-compliance elsewhere in the supply chain. That means a business may face consequences even when it was not the direct party withholding tax, operating a fraudulent payroll arrangement or claiming a false CIS credit.

    The immediate exposure can include a determination of up to 20% of the relevant payment, a penalty of 30% of that determination, and the cancellation of Gross Payment Status. In serious cases, the business may be prevented from reapplying for Gross Payment Status for five years, while penalties may also be transferred to individual company officers.

    This is not simply another filing rule. It is a supply-chain responsibility test.

    The HMRC CIS fraud guidance confirms that the new powers apply to payments for construction operations and CIS credits claimed on or after 6 April 2026. Construction News has now reported that HMRC is actively targeting payroll fraud involving criminal umbrella companies, while Construction Management has warned that the absence of public cases does not mean contractors are safe.

    For contractors in Essex, Kent, London and throughout the UK, these are the five checks that should be completed before the next CIS review or HMRC enquiry.

    Contractor reviewing subcontractor identity, CIS and PAYE compliance documents

    1. Document your supply-chain due diligence

    The first question is not whether you have checked a subcontractor once. It is whether you can show what you checked, when you checked it, what you found and what you did with the information.

    A basic verification of a subcontractor’s UTR and CIS status is still important, but it may not be enough where the wider arrangement raises concerns. HMRC is looking at the reality of the labour supply chain, including agencies, payroll companies, umbrella providers and any onward subcontracting.

    Your due-diligence file should normally consider:

    • Company registration and trading history
    • VAT registration where relevant
    • Directors, owners and connected businesses
    • CIS registration and payment status
    • PAYE arrangements for labour supplied through an agency or umbrella
    • Evidence that workers receive proper payslips and deduction statements
    • References and previous project history
    • The identity of the party actually paying the workers
    • Any onward subcontracting or changes in the payment route

    It is also important to repeat checks periodically. Continuous due diligence is more credible than an onboarding form completed several years ago and never reviewed again.

    Construction News reported on 15 September that HMRC’s current campaign is focused on payroll fraud where income tax, National Insurance and CIS deductions are taken from workers but not passed to HMRC. The article’s practical message is clear: contractors should know who their suppliers are, who pays the workers and whether the deductions shown on payslips are being accounted for.

    A concern is not automatically a breach. But an unexplained concern that is ignored is much harder to defend.

    2. Benchmark labour rates against market norms

    Unusually low pricing is one of the clearest warning signs in a supply chain. It does not prove fraud, but it should prompt questions.

    A labour provider offering rates materially below the market may be benefiting from genuine efficiencies. Equally, the price may only be possible because PAYE, National Insurance, CIS deductions, VAT or minimum wage obligations are not being dealt with properly.

    Contractors should therefore retain evidence of how rates were assessed. This might include:

    • Comparable quotes from other labour providers
    • Published wage or industry data
    • Project cost plans
    • Records of conversations with the supplier
    • Explanations for significant differences in price
    • Confirmation of what the rate includes, such as holiday pay, employer costs and payroll administration

    Contractor comparing labour rates and invoices against a construction market benchmark

    A low quote becomes more concerning when combined with other issues, such as an unclear contract, multiple layers of intermediaries or a supplier with very little relevant trading history.

    This is where the “should have known” test becomes uncomfortable. HMRC does not necessarily need to show that the contractor understood the fraud. It may ask whether a reasonable contractor would have challenged the commercial arrangement before making payments.

    The answer should not be based on hindsight. A properly documented pricing review gives you evidence of what was known and considered at the time.

    3. Investigate red flags rather than simply recording them

    Many businesses have policies that list risk indicators, but the real test is what happens after a red flag appears.

    Possible warning signs include:

    • A labour rate that is too low to appear commercially realistic
    • Frequent changes in the contracting entity or bank account
    • A supplier that refuses to explain its ownership or payment process
    • Workers receiving unclear, inconsistent or missing payslips
    • A company with no obvious construction experience supplying a large workforce
    • Several layers of agencies or subcontractors with no clear commercial purpose
    • Pressure to make payments to a different entity
    • Invoices that do not match the work completed
    • A supplier unwilling to provide evidence of PAYE, VAT or CIS compliance
    • Significant labour costs being paid without a formal written agreement

    Contractor investigating a warning sign in a construction labour supply chain

    A red flag should lead to a proportionate response. That might involve asking for further documents, pausing a payment, obtaining independent tax advice, reducing the number of intermediaries or ending the relationship.

    The important point is to record the decision and the reason for it. “We have always used them” is not a control. Neither is “the price was attractive”.

    The HMRC penalty factsheet explains that penalties can apply where a business knew or should have known that a payment or CIS credit was linked to deliberate non-compliance by a connected party.

    4. Obtain written assurance and keep a proper audit trail

    A supplier’s verbal assurance is useful, but it is not a complete compliance process. Contractors should use written agreements that clearly explain who is responsible for payroll, PAYE, National Insurance, CIS deductions, VAT and worker documentation.

    Depending on the arrangement, you may also want to request:

    • Written confirmation of the supplier’s payroll model
    • Evidence of relevant registrations
    • Sample payslips with personal information removed
    • Confirmation of how deductions are calculated and paid
    • Contractual rights to audit or request supporting records
    • Notification requirements for changes in ownership, bank details or onward subcontracting
    • Warranties concerning compliance with tax and employment obligations

    The audit trail should connect the evidence to the decision. It should show who approved the supplier, who reviewed any warning signs and what follow-up took place.

    Construction Management’s September analysis makes an important point: HMRC enquiries may take time and may not become public until a dispute reaches a tribunal. Silence therefore does not mean that the regime is inactive. It gives contractors an opportunity to improve their records before an enquiry letter arrives.

    It is worth training commercial managers, project managers, procurement teams and finance staff so that concerns do not remain isolated in one department. A project manager may notice a change in labour behaviour before the finance team sees an unusual payment pattern.

    5. Make sure your insurance declarations match reality

    Insurance will not pay an HMRC tax determination or a CIS penalty. These are financial liabilities arising from tax and regulatory non-compliance, not accidental third-party losses. A policy also cannot restore Gross Payment Status after it has been cancelled.

    That does not mean insurance is irrelevant.

    The due-diligence failure that contributes to an HMRC problem may also indicate a wider risk-management weakness. Insurers and surety providers are increasingly interested in how contractors use labour-only subcontractors, agencies and other supply-chain partners. Your answers can affect underwriting, policy terms, premiums and bond capacity.

    When reviewing your Construction Contractor Insurance or General Contractor Liability Insurance, check that your declarations accurately describe:

    • The proportion of work completed by subcontractors
    • Whether subcontractors are labour-only or bona fide
    • The trades and activities being undertaken
    • The size and value of projects
    • The use of temporary labour, agencies or umbrella companies
    • Who supervises subcontracted workers
    • Whether subcontractors carry their own liability insurance
    • Whether your policy requires evidence of that insurance

    Construction contractor checking that insurance declarations match the real subcontracting arrangement

    A standard public liability policy is not a substitute for tax compliance, but it remains important protection against injury, property damage and other insured claims arising from construction work. Moyak’s commercial combined insurance can include public liability, employers’ liability, business interruption and legal expenses, depending on the policy selected.

    Legal expenses or tax protection sections may assist with certain professional costs connected to an investigation, subject to the wording, limits and exclusions. They should not be confused with cover for the underlying tax, determination or penalty.

    The wider risk picture for contractors

    The timing matters. The Building Safety Levy is due to take effect on 1 October 2026, while Ardmore’s Building Liability Order appeal is listed for 15 December. Recent TCC decisions also continue to test how liability may reach connected companies and wider project participants.

    These issues are different from CIS fraud, but they point in the same direction: construction businesses are being expected to understand more than their immediate contract. Group structures, labour arrangements, payment flows and governance all matter.

    That is why insurance reviews should be practical rather than purely administrative. At Moyak Insurance Services, our individual approach means we ask how your business actually operates, not just which box appears easiest to tick. We work with businesses across Essex, Kent and London and can help assess whether the insurance information provided to insurers reflects your current work.

    If you are looking for Business Insurance Essex or Business Insurance London, the starting point should be an honest review of the risk, including your subcontracting model and supply-chain controls.

    What to do this week

    Before your next CIS audit or HMRC enquiry:

    1. Map every active subcontractor, agency and labour provider.
    2. Check who actually pays the workers.
    3. Review labour rates that appear unusually low.
    4. Investigate and document every material red flag.
    5. Refresh contracts and written compliance assurances.
    6. Check that your CIS returns and records are complete.
    7. Review your insurance proposal forms and policy schedule.
    8. Speak to your accountant or tax adviser about the new rules.

    The new regime does not require contractors to guarantee that nobody in their supply chain will ever breach a tax obligation. It does require them to act reasonably, investigate concerns and retain evidence of those decisions.

    That is the practical standard now. Strong due diligence will not make every construction risk disappear, but it can help demonstrate that your business did not ignore the warning signs. And it may protect more than your CIS position: it can also support better insurance terms, stronger insurer confidence and more sustainable bond capacity.

    This article is for general information and is not tax or legal advice. Contractors should obtain advice on their own CIS arrangements and review their insurance policy wording with a qualified broker.

  • Can a Building Liability Order Reach Your Company? 5 Lessons From the Ardmore Collapse Every General Contractor Needs

    Can a Building Liability Order Reach Your Company? 5 Lessons From the Ardmore Collapse Every General Contractor Needs

    For general contractors, the Ardmore collapse is a warning that historic building safety liabilities can move far beyond the company that originally carried out the work. It is also a reminder that General Contractor Liability Insurance is not automatically designed to respond to every liability created by the Building Safety Act 2022.

    In June 2026, parts of the Ardmore Construction Group entered administration after a £14.9 million Building Liability Order connected to defects at Admiralty Quarter in Portsmouth. Around 275 jobs were lost, subcontractors faced an estimated £5.1 million exposure, and the surety market was reported to be facing potential losses of up to £100 million.

    The project had been completed in 2009.

    That combination matters. A liability arising from an old project reached seven related group companies, contributed to a major contractor failure and created consequences for employees, subcontractors, developers, insurers and bond providers.

    The High Court decision remains subject to appeal, but the practical message for general contractors is already clear: corporate structures, old project files and standard insurance assumptions all need closer examination.

    What happened in the Ardmore case?

    Ardmore Construction was engaged to design and build the Admiralty Quarter development, comprising 19 residential buildings in Portsmouth. Construction took place between 2007 and March 2009.

    Following post-Grenfell investigations, concerns were raised about fire safety defects involving external wall systems, combustible materials, compartmentation and fire stopping. In August 2025, an adjudicator found Ardmore liable under the Defective Premises Act 1972 and awarded approximately £14.9 million.

    Ardmore Construction entered administration. Crest Nicholson then applied for Building Liability Orders under sections 130 and 131 of the Building Safety Act, seeking to extend the relevant liability to associated group companies.

    On 1 April 2026, the Technology and Construction Court granted both an anticipatory BLO and an order making seven associated Ardmore companies jointly and severally liable for the adjudicated sum. The Court’s approach showed that a claimant does not necessarily have to stop at the original contracting entity where the wider corporate group is associated with it and extending liability is considered just and equitable.

    This is not a general removal of separate legal personality. It is a statutory route that can, in practical terms, reach beyond the company that signed the original contract.

    Hand-drawn illustration of a contractor group structure with related companies connected by highlighted lines

    Lesson 1: A BLO can target the group, not just the insured company

    Many contractors insure each trading entity separately. That can be sensible for accounting, contracting and operational reasons, but it does not mean that risk is neatly separated when the Building Safety Act applies.

    A Building Liability Order may extend a relevant liability from the original company to associated companies. The Court will consider the facts, the corporate relationships, the history of the liability and whether it is just and equitable to make the order.

    For a general contractor, the first practical exercise is therefore a group structure review.

    Ask:

    • Which company signs construction contracts?
    • Which company employs site staff?
    • Which company owns plant, property or retained profits?
    • Are historic liabilities held in a different entity?
    • Have businesses been reorganised, transferred or placed under a new parent?
    • Do policy schedules identify every relevant company?
    • Do the insurance wordings include the correct subsidiary and associated company provisions?

    A policy covering the main trading company may not respond in the same way to a statutory liability imposed on another group company. Even where an extension exists, there may be different limits, conditions, aggregation provisions and exclusions.

    This is where a broker’s involvement matters. A proper review should look at the group chart and the claims history alongside the policy wording, rather than treating a certificate of insurance as the complete answer.

    Lesson 2: Legacy projects do not simply disappear

    The Ardmore project was completed in 2009. That is a long time in construction. People change jobs, companies restructure, records move to storage and insurers may be replaced several times.

    The Building Safety Act introduced significant changes to how historic building safety claims can be pursued, including extended limitation periods for certain claims. The result is that a project which appeared closed may still create financial and legal exposure many years later.

    Hand-drawn illustration of a completed residential building, an old blueprint and a timeline from 2009 to the present

    This creates a particular challenge for SMEs. Larger contractors may have dedicated legal, technical and compliance teams, but smaller firms often rely on directors remembering what happened and where the documents were kept.

    That approach is not robust enough.

    For each significant project, retain:

    • The contract and amendments
    • Design responsibility records
    • Employer’s requirements and specifications
    • Subcontractor appointments
    • Product and material approvals
    • Inspection and test plans
    • Building control correspondence
    • Fire strategy and engineering documents
    • Site photographs
    • Completion certificates
    • Defect and remediation records
    • Details of the insurers notified at the time

    Good records will not remove liability, but they can help establish what was designed, supplied, inspected and approved. They may also support contribution claims against designers, subcontractors, manufacturers or other responsible parties.

    Lesson 3: Insurance exclusions are different from uninsurable liabilities

    A common assumption is that if a company has public liability or Construction Contractor Insurance, the insurer will deal with any claim arising from defective construction work.

    That is not how most policies operate.

    Public liability insurance is generally intended to cover legal liability for injury to third parties or accidental damage to third-party property. It is not automatically a warranty that the contractor’s work will be fit for purpose. The cost of correcting defective work, improving a design or replacing faulty materials may be excluded, particularly where the loss is treated as a contract liability or a rectification cost.

    A Building Liability Order creates an additional complication. It is a statutory mechanism that can make an associated company jointly and severally liable for a relevant liability of the original body. A standard policy may not have been written to respond to that type of exposure, particularly where:

    • The company was not the original contracting party
    • The liability relates to a project completed many years ago
    • The claim concerns fire safety or structural defects
    • The loss is a remediation cost
    • The policy contains defective workmanship or contract liability exclusions
    • The company was not named as an insured at the relevant time

    That does not mean every BLO-related claim is automatically uninsured. It means the answer depends on the specific policy wording, the applicable policy period, the nature of the underlying liability and how the claim is presented.

    Directors should not wait for a claim before asking these questions. Our earlier guide on the clause in contractors insurance that could leave you uncovered explains why the detail of a contractors policy matters.

    Lesson 4: Bonds and retentions are changing the risk conversation

    The construction sector has relied heavily on retentions, parent company guarantees and performance bonds to manage project risk. That balance is changing.

    The proposed Small Business Protections (Late Payments) Bill includes reforms aimed at restricting payment terms to 60 days and banning construction retentions, subject to parliamentary passage and implementation arrangements. The Bill does not necessarily require every retention to be replaced with a surety bond, but the commercial effect is likely to increase pressure on contractors and clients to find alternative security.

    That is important because surety capacity has already been tested by contractor failures including Buckingham, ISG, Readie and Henry. Market reporting has put the wider UK surety market at roughly £200 million of annual premium in normal conditions, while construction bond premium volumes have at times exceeded £1 billion as demand and pricing increased.

    The Ardmore failure adds another major loss event. Performance bonds may be called when projects stop, contracts are terminated or replacement contractors are appointed. Subcontractors, meanwhile, may lose retentions and unpaid applications at the same time.

    For general contractors, the practical actions are to:

    • Understand every bond, guarantee and indemnity given to a client
    • Check whether the bond is on-demand or conditional
    • Model the cash-flow impact of a bond call
    • Review counter-indemnity obligations
    • Keep payment applications and variations properly documented
    • Discuss bond requirements with your broker before signing a contract

    Hand-drawn illustration of a surety bond, shield, hard hat and organised project records

    Lesson 5: Evidence-based governance is becoming part of insurability

    The construction industry often talks about the “golden thread” in relation to building safety information. For contractors, the wider principle is straightforward: insurers, courts, developers and funders increasingly want evidence, not assurances.

    It is not enough to say that a competent person inspected the work. You should be able to show who inspected it, when they did so, what they found, what was changed and who approved the change.

    Insurers are likely to look favourably on contractors that can demonstrate:

    • Clear responsibility for design and compliance
    • Formal approval of material substitutions
    • Consistent site inspection records
    • Documented subcontractor competence checks
    • A controlled process for variations
    • Regular board review of legacy liabilities
    • A live register of claims, complaints and potential defects
    • Proper notification to insurers when circumstances arise

    This is not about producing paperwork for its own sake. It is about being able to reconstruct decisions years later, when the people involved may no longer be available.

    What should general contractors do now?

    The Ardmore case does not mean every construction business faces a £14.9 million claim. It does mean that a standard liability certificate is not a complete risk-management strategy.

    I recommend that general contractors arrange a structured review covering:

    1. Corporate structure: Identify every company that has carried out, owned or benefited from construction work.
    2. Legacy projects: Create a register of completed projects, particularly residential and higher-risk buildings.
    3. Insurance wording: Check defective work, contract liability, pollution, professional services and building safety provisions.
    4. Bonds and guarantees: Understand the financial consequences of calls and counter-indemnities.
    5. Records: Confirm that project information is accessible, complete and securely retained.
    6. Broker engagement: Ask for advice before renewing, restructuring or accepting a major contract.

    At Moyak Insurance Services, we take an individual approach because no two contractors have the same projects, group structure or appetite for risk. As a Business Insurance Broker serving Essex, Kent and London, we work with leading UK insurance markets to assess the cover against the work you actually undertake, not just the description written on a proposal form.

    Our focus is simple: care about every client, identify the gaps early and help you choose protection that fits your business and budget. That may include a broader commercial combined insurance policy, public liability, employers’ liability, professional indemnity, contract-specific insurance or advice on bonds and guarantees.

    The key lesson from Ardmore is not to panic. It is to stop assuming that a liability belongs only to the company that carried out the work, or that a standard policy will automatically follow it. Review your group structure, revisit your old projects and ask your broker to explain what your insurance does : and does not : cover before a Building Liability Order makes the question urgent.

    This article is for general information only and is not legal advice. The Ardmore proceedings and related appeal may continue to develop. Contractors should obtain specific legal and insurance advice based on their own circumstances.

    Sources and further reading

  • 42% of Small Businesses Were Hacked in 2025 : Is Your Construction Firm Next? (5-Minute Cyber Check for Contractors)

    42% of Small Businesses Were Hacked in 2025 : Is Your Construction Firm Next? (5-Minute Cyber Check for Contractors)

    Cyber risk is no longer an office-only problem. For construction contractors, it now sits inside the everyday workflow: BIM models, project portals, payment instructions, subcontractor records, email accounts and cloud-based document systems.

    The headline figure is difficult to ignore. Around 42% of small businesses were reported as experiencing a cyber breach or attack in 2025, although the Government’s terminology is worth explaining. The official Cyber Security Breaches Survey 2025 recorded 42% of small businesses reporting phishing attacks and 50% identifying any breach or attack. Either way, the practical message is the same: contractors are not too small to be targeted.

    The same survey found that only 62% of small businesses had some form of cyber insurance, meaning roughly 35% to 40% did not. Cost is one reason, but unclear advice is another. Many business owners are unsure whether their existing commercial policy covers a payment scam, ransomware, data breach or the cost of recovering a project system.

    That uncertainty is the gap contractors need to close.

    Why construction businesses are exposed

    Construction firms may not think of themselves as technology businesses, but many now depend on digital systems to keep projects moving.

    A typical contractor could be using:

    • BIM and digital design files
    • Cloud-based project portals and common data environments
    • Email approval chains for variations and payments
    • Accounting and CIS systems
    • Subcontractor bank details and payroll records
    • Mobile devices used by site managers and commercial teams
    • Shared folders containing tenders, pricing and technical documents

    Each system creates another route into the business. A compromised email account may allow a criminal to monitor payment discussions for several weeks before sending a convincing request to change a subcontractor’s bank details. A stolen project-portal login may expose drawings, specifications and commercial information. Ransomware affecting a document system can delay decisions, valuations and handovers even when no physical damage has occurred.

    The National Cyber Security Centre’s small organisations guidance makes the sensible point that many protective measures can be completed in minutes. Contractors do not need to become cyber-security specialists, but they do need to know what they rely on and where the financial consequences would fall.

    Five-minute cyber check for contractors with icons for MFA, backups, phishing, payment verification and insurance

    The five-minute cyber check

    1. Can someone access your key accounts with a password alone?

    Check email, finance systems, BIM platforms and project portals. If important accounts do not have multi-factor authentication, or MFA, enabled, that should be treated as a priority.

    MFA is not perfect, but it makes a stolen password much less useful to an attacker. It should be applied to directors’ accounts, finance staff, commercial managers, administrators and anyone with access to project or payment systems.

    Also check whether former employees, temporary staff and completed subcontractors still have access. In construction, access can remain in place long after a project role has ended.

    2. Could you recover your project files tomorrow?

    Backups are only useful if they are separate from the systems being attacked and have been tested. Ask:

    • Are BIM files and project documents backed up?
    • Are finance and CIS records included?
    • Are backups protected from ordinary user accounts?
    • When was the last successful restoration test?
    • Could the business continue if the main portal was unavailable for several days?

    The Government survey found that temporary loss of access to files or networks was one of the most common negative outcomes reported by businesses. For contractors, the resulting cost may include overtime, rework, delayed payment applications, contractual arguments and lost management time.

    3. Would your team verify a bank-detail change by telephone?

    Email instructions are not enough for payment changes. A criminal who has compromised an account may know the names of the project manager, quantity surveyor and subcontractor, and may understand exactly when a payment is due.

    Set a simple rule: any change to bank details must be confirmed using a known telephone number already held on your records, not a number included in the email. Larger payments should also require a second approval and, where practical, separation between setting up a payee and releasing funds.

    This is one of the most important controls for a contractor because a payment-fraud loss may not be treated in the same way as a direct hacking incident.

    4. Do you know what your existing insurance actually covers?

    Do not assume that a standard Construction Contractor Insurance policy automatically provides broad cyber protection.

    Public liability, employers’ liability, contract works and professional indemnity each respond to different types of risk. Some commercial policies may include limited cyber-related extensions or legal expenses, but that is not the same as having a dedicated cyber policy designed around your systems and exposures.

    A cyber policy may provide cover for areas such as:

    • Incident response and forensic investigation
    • Legal and regulatory advice
    • Data breach notification and communication costs
    • Cyber extortion and ransomware, subject to policy terms
    • Business interruption following a covered cyber event
    • Restoration of data and systems
    • Certain forms of funds-transfer or social-engineering fraud
    • Third-party claims arising from a data or network security failure

    The wording matters. A policy may cover a direct funds-transfer fraud but exclude a loss caused by an employee approving a fraudulent request. It may cover network interruption but not a delay penalty under a construction contract. It may respond to data restoration but not the cost of correcting defective work after a project file has been altered.

    The right question is not simply, “Do we have cyber insurance?” It is, “Which of our actual construction exposures are insured, and which are not?”

    5. Is your incident plan written down?

    If an account is compromised at 8.30am on a Monday, people need to know what happens next. The first steps may include contacting the bank, isolating devices, preserving evidence, notifying the insurer and engaging an approved incident-response provider.

    Write down:

    1. Who makes the initial decision?
    2. Who contacts the bank and IT provider?
    3. Which insurer or broker must be notified?
    4. Who communicates with clients and subcontractors?
    5. Where are emergency contact details stored if systems are unavailable?

    Insurers increasingly want evidence of sensible controls, including MFA, secure backups, patching and an incident-response process. Better controls can also improve the quality of the insurance submission and help avoid unnecessary premium increases.

    What cyber insurance will not solve

    Insurance is not a substitute for good security, and it cannot turn every construction loss into an insured claim.

    Criminal fines remain uninsurable as a matter of public policy. A fine imposed following a breach of the Health and Safety at Work etc. Act 1974 is not something a policy should be expected to pay. Defence costs and legal assistance may be covered under some policies, but the penalty itself is not.

    This distinction matters because the regulatory environment is becoming less forgiving. The courts are also taking a harder approach to building safety responsibilities. Under the Building Safety Act 2022, a Building Liability Order can extend certain liabilities to associated companies where the court considers it just and equitable. Remediation Contribution Orders can also create significant civil exposures in the right circumstances.

    Those are not cyber risks, but they show why contractors should not view insurance as a replacement for records, controls or compliance. Courts and regulators are unlikely to accept that a contractor’s insurance position excuses poor conduct.

    What about the softer professional indemnity market?

    There is some better news elsewhere. London construction professional indemnity renewal rates are expected to soften by around 5% to 10% in 2026 for good risks, with stronger results possible for well-managed businesses with good claims records and well-presented submissions.

    That is welcome, but it does not remove the need to review cyber cover. Professional indemnity may respond to certain design or advisory liabilities, while cyber insurance deals with a different set of first-party and network-related events. There can be overlap, but there can also be gaps, particularly where a cyber incident causes project delay, payment fraud or loss of access to digital information.

    Construction contractor reviewing cyber, professional indemnity and business insurance with a broker

    A practical next step for contractors

    At Moyak, we see the same problem regularly: businesses have bought insurance, but nobody has tested whether the cover reflects how the business operates today.

    Our approach is individual rather than transactional. We take time to understand the contractor, the projects, the supply chain, the systems being used and the budget available. As a Business Insurance Broker in Essex, Kent and London, we work with leading master brokers and insurers to compare suitable options rather than forcing every client into the same package.

    If your business uses BIM, project portals, online payment approvals or stores sensitive subcontractor and client data, ask for a structured review of your general contractor insurance and cyber exposures. We can also look at how cyber insurance sits alongside professional indemnity, public liability, employers’ liability and commercial combined insurance.

    The five-minute check is a starting point, not a complete risk assessment. But it should quickly show where the most urgent gaps are.

    Check the accounts. Test the backups. Verify payment changes. Read the exclusions. Write down the response plan.

    That is how contractors move from hoping their insurance will respond to understanding what protection they have before a breach does the testing for them.

  • The 2026 Rate Drop Is Real : So Why Is Your General Contractor Liability Insurance Renewal Still Going Up? (5 Fixes That Work)

    The 2026 Rate Drop Is Real : So Why Is Your General Contractor Liability Insurance Renewal Still Going Up? (5 Fixes That Work)

    The UK construction insurance market is softening in 2026, but that does not mean every contractor will automatically receive a cheaper renewal.

    In fact, many well-managed construction businesses are seeing better terms. New capacity has entered the market, insurers are competing more actively and some strong construction risks are achieving reductions of 5–10% or more, depending on their claims history, cover and presentation.

    But the picture is uneven, particularly for General Contractor Liability Insurance.

    Annual liability programmes are generally seeing more controlled reductions than project-specific placements. Recent construction market commentary suggests that annual contractor programmes may achieve savings of around 5% in suitable cases, while some project placements and well-performing accounts are seeing greater competition. At the same time, insurers remain cautious about legacy liabilities, incomplete records, higher-risk work and businesses whose insurance programme has not kept pace with their growth.

    This is why a contractor can hear that rates are falling across the market and still receive a renewal increase.

    The good news is that there are practical steps you can take before renewal. Here are five fixes that can make a material difference.

    1. Rebuild your risk profile before the insurer does it for you

    One of the most common problems I see is that a contractor’s renewal information describes the business as it was several years ago.

    The company may now have a different turnover, larger contracts, more employees, new subcontractors, additional work at height or a greater involvement in design and project management. Yet the insurer is still working from an old trade description and a short renewal form.

    That creates two problems. First, the insurer may price the risk conservatively because it does not have enough detail. Second, the policy may not accurately reflect what the business now does.

    Before renewal, prepare a clear summary covering:

    • Current turnover and expected turnover
    • The type and value of projects undertaken
    • The percentage of work carried out by subcontractors
    • The geographical area in which you operate
    • Work involving refurbishment, structural alterations or occupied premises
    • Any design, specification or consultancy responsibilities
    • The number of employees and use of temporary labour
    • Plant, tools, vehicles and equipment
    • Claims, incidents and near misses

    This is not about presenting the business in the best possible light. It is about presenting it accurately.

    A specialist broker can then approach insurers with a properly updated risk profile rather than allowing an automated renewal process to make assumptions on your behalf.

    2. Put evidence behind your risk management

    Insurers are increasingly rewarding traceable decisions and evidence-based governance, not just broad statements that a company has “good health and safety.”

    That does not mean every contractor needs a large compliance department. It does mean you should be able to show how you manage foreseeable risks and who is responsible for key decisions.

    Useful evidence may include:

    • Site induction and toolbox-talk records
    • Risk assessments and method statements
    • Training records
    • Inspection and maintenance logs
    • Subcontractor vetting procedures
    • Accident and near-miss reporting
    • Site photographs
    • Health and safety audit results
    • Written design responsibility and approval processes
    • Fire safety and cladding-related reviews where relevant

    The quality of the evidence matters more than the volume. A well-organised file showing a consistent process is usually more helpful than a large collection of disconnected documents.

    Construction insurance documentation, safety records and project evidence arranged for an underwriting review

    For contractors with design-and-build responsibilities, insurers may also want to understand who made design decisions, whether responsibilities were novated and how technical changes were reviewed. Clear records can help distinguish a controlled risk from one where responsibility is uncertain.

    This is particularly important for contractors involved in structural work, higher-risk buildings, fire safety, cladding or complex refurbishment. These areas continue to receive more scrutiny, even while the wider market softens.

    3. Investigate legacy liabilities instead of leaving them in the background

    A renewal increase is sometimes driven less by what you are doing today and more by what the insurer believes may still emerge from older work.

    Construction liabilities can develop slowly. A project completed several years ago may later produce a defect allegation, a third-party injury claim or a dispute about who was responsible for the design. The fact that there has not yet been a claim does not necessarily mean an insurer will regard the exposure as closed.

    This is particularly relevant where a business has:

    • Worked on older residential or mixed-use developments
    • Been involved in structural alterations
    • Used external designers or consultants
    • Accepted contractual responsibility beyond its actual role
    • Worked on buildings with cladding or fire safety concerns
    • Taken over projects from another contractor
    • Closed, merged or changed its trading structure

    Before renewal, prepare a simple historic project summary. Identify the project, dates, client, scope of work, design responsibilities, subcontractors and any known issues. You do not need to produce a forensic report for every project, but you should know where the main exposures are.

    Insurers do not necessarily expect every historic risk to be perfect. They want to see that you understand it and have a proportionate process for reviewing it.

    That can lead to a more constructive underwriting conversation than simply answering “no known claims” on a renewal form.

    4. Check that your limits, turnover and contract works values still make sense

    The headline premium is important, but it is only one part of the renewal.

    The bigger risk is saving money by reducing limits or leaving sums insured out of date. A business that has grown can be underinsured without realising it. This is a particular issue for small and medium-sized firms, which sometimes insure who they were rather than who they are now.

    Review:

    • Public liability and products liability limits
    • Employers’ liability requirements
    • Contract works values
    • Hired-in plant and equipment
    • Tools and equipment kept on site
    • Goods in transit
    • Business interruption or increased cost of working
    • Professional indemnity where design responsibility exists
    • Any contractual insurance requirements imposed by clients

    Construction costs, labour costs and project values have changed significantly in recent years. A contract works limit that looked adequate at the last renewal may no longer reflect the largest project you undertake.

    The same applies to turnover. If the business has expanded but the policy still records an old turnover figure, the insurer may apply the wrong rating basis and the cover may not respond as expected after a claim.

    A lower premium is not a good result if it is achieved by creating a substantial coverage gap.

    5. Start the renewal early and test the market properly

    Leaving a contractor insurance renewal until the final week is rarely helpful, particularly where the business has a complex claims history or works across Essex, Kent, London and beyond.

    A proper renewal exercise takes time because the broker needs to understand the business, prepare the information and approach suitable markets. It may also be necessary to obtain clarification from underwriters about exclusions, excesses, subcontractor conditions or project-specific requirements.

    Starting early gives you time to:

    • Correct inaccurate policy information
    • Gather claims details
    • Review contract requirements
    • Compare alternative insurers
    • Negotiate terms rather than simply accept them
    • Consider whether a package policy is still appropriate
    • Separate risks that need specialist treatment
    • Resolve questions about historic work

    This is where local knowledge can be useful. Contractors in Essex may have access to local brokers who understand the regional market, while also being able to access the capacity and specialist expertise available through London insurance markets.

    At Moyak Insurance Services, we take an individual approach rather than treating every contractor as a standard trade category. Our general contractor insurance service is designed for businesses including local building contractors, developers and roofing contractors, with cover considered across areas such as employers’ liability, public liability, products liability, contract works, hired-in plant and employees’ tools.

    The aim is not simply to find the lowest initial quotation. It is to help make sure the policy reflects the actual business and provides sensible protection for its financial interests.

    Broker and construction business owner reviewing policy limits, turnover and contract works cover

    What the 2026 construction reforms could mean for contractors

    The market is also developing against a backdrop of proposed legislative change.

    The Government’s King’s Speech 2026 background briefing notes refer to action intended to ban the deduction and withholding of retention payments under construction contracts. The proposal is not the same as an insurance excess or self-insured retention, but it could affect contractor cash flow, payment arrangements and contract negotiations.

    There is also continuing building safety and remediation reform, including proposals affecting construction products and unsafe cladding. These measures are still developing, so contractors should not assume that future legal responsibilities will be automatically covered by an existing liability policy.

    Before renewal, review your contracts and discuss the wording with your broker, especially if you:

    • Accept responsibility for design or construction performance
    • Work within a supply chain with extensive indemnity obligations
    • Receive or pay retention amounts
    • Work on higher-risk buildings
    • Rely on subcontractors’ professional indemnity policies
    • Have historic exposure to cladding or fire safety issues

    The important point is not to panic or buy every available extension without understanding it. It is to identify where contractual responsibilities and insurance cover may no longer align.

    A softer market still rewards better preparation

    The 2026 rate environment is encouraging, but it is not a blanket price reduction for every contractor.

    Insurers are competing for well-managed business, while remaining disciplined about claims, legacy liabilities, complex construction and poor-quality information. Contractors who provide clear evidence, review their limits and approach the market early are more likely to benefit from the available competition.

    If your General Contractor Liability Insurance renewal has increased despite wider rate softening, do not assume the market is simply working against you. Ask what has changed in the insurer’s view of your risk and whether the information being used is still accurate.

    Moyak Insurance Services provides business insurance support for contractors and growing firms across Essex, Kent and London. We care about every client and take the time to understand the business behind the policy. To arrange a review, visit our business insurance contact page.

    The information in this article is for general guidance and does not replace advice on your individual insurance arrangements or contractual obligations. Proposed legislation may change before it becomes law.

    Sources

  • £1.15m in Fines for a Trench Death: What Every Groundworks Contractor Needs to Understand About Insurance

    £1.15m in Fines for a Trench Death: What Every Groundworks Contractor Needs to Understand About Insurance

    A fatal trench collapse on a construction site in Banstead, Surrey has resulted in more than £1 million in criminal fines, alongside a suspended prison sentence for a contracts manager.

    The case is a serious reminder for groundworks contractors, demolition contractors, civil engineering firms, principal contractors and construction business owners across Essex, Kent and London. A major site incident does not create one financial problem. It creates several, and insurance only responds to some of them.

    The court proceedings followed the death of Gheorghita Arsene, who was fatally crushed when a deep trench collapsed at a Surrey construction site in June 2020. His death was tragic, and the HSE has described it as preventable. The case also raises important questions about employers’ liability insurance, criminal fines, the Employers’ Liability Tracing Office and what happens when a contractor later goes into liquidation.

    What happened at the Banstead site?

    Gheorghita Arsene was working at a construction site in Banstead, Surrey, where a damaged pipe was being replaced at the bottom of a deep excavation.

    The trench had no suitable supports in place, and excavated soil had been piled close to its edge. The trench walls collapsed, burying Mr Arsene under approximately two tonnes of soil. Despite rescue attempts, he sadly died at the scene.

    Following a three-month trial at the Old Bailey, Appledorn Developments Limited and T Vaughan Limited were found guilty of offences under the Health and Safety at Work etc. Act 1974. Contracts manager Anthony O’Connor admitted the same charge of failing to discharge his duties.

    Judge Judy Khan fined:

    • Appledorn Developments Limited: £500,000
    • T Vaughan Limited: £650,000, plus £40,000 in costs, with six years allowed for payment

    The now-defunct Appledorn was criticised for failing to provide a safe system of work and for being motivated by a desire to complete the work quickly and cheaply. T Vaughan had systems in place, but the court found that they had not been sufficiently implemented.

    Mr O’Connor received a sentence of 10 months’ custody, suspended for 18 months, and was ordered to complete 150 hours of unpaid work. The judge found that he had “actual foresight” of the risk of harm.

    The HSE’s account of the prosecution makes the central point plainly: basic precautions were not in place despite the well-known risks associated with excavation work.

    The three financial consequences of a serious incident

    From an insurance perspective, the most important lesson is that a fatal incident usually develops along three separate tracks.

    Three-panel illustration showing criminal fines, civil compensation and underwriting consequences

    1. The criminal fine is paid by the business

    Criminal fines cannot be insured. That is settled UK insurance law and public policy.

    The reason is straightforward. A fine is intended to punish and deter criminal conduct. If a company could simply pass the fine to its insurer, the deterrent effect would be undermined. Therefore, the £500,000 and £650,000 fines in this case sit with the businesses themselves, regardless of any employers’ liability, public liability or construction policy they may have held.

    This is worth stating clearly because businesses sometimes assume that a broad Construction Contractor Insurance package will respond to every cost following an accident. It will not cover the criminal penalty itself.

    The same principle applies to a director or manager. A policy may, depending on its wording, provide defence costs for certain regulatory or health and safety proceedings, but it will not lawfully pay a criminal fine imposed on an individual.

    2. The civil compensation claim is separate

    The criminal prosecution is not the same as the civil claim brought by Mr Arsene’s family.

    The two processes involve different legal tests, different procedures and different financial outcomes. The criminal court decides whether an offence has been committed and imposes a sentence. A civil claim considers compensation for the death and related losses, and may be settled or contested independently of the criminal proceedings.

    This is where employers’ liability insurance is designed to respond.

    Under the Employers’ Liability (Compulsory Insurance) Act 1969, most UK employers must hold employers’ liability cover. The statutory minimum is £5 million, while many policies provide £10 million or more. The cover is intended to fund compensation claims and associated legal costs where an employee is injured, becomes ill or dies because of their work.

    That does not mean every claim is automatically paid. Liability, causation, policy terms, limits and exclusions still matter. But employers’ liability insurance exists specifically for this type of civil exposure.

    3. The underwriting and reputational record remains

    The third consequence is less immediate but can affect the business for years.

    HSE enforcement actions and convictions are public record. Insurers already consider claims experience, health and safety procedures, subcontractor controls and enforcement history when assessing construction risks. Clients awarding tenders may also ask about prosecutions, improvement notices and serious incidents.

    For T Vaughan, which continues to trade and has been given six years to pay its fine, the conviction will form part of the firm’s future risk profile. It may influence renewal terms, premiums, excesses, available limits and the number of insurers willing to offer terms.

    It may also affect tender decisions. A conviction does not automatically make a contractor uninsurable, but it does mean that future insurers and clients are likely to ask more questions.

    What happens if the contractor goes into liquidation?

    Appledorn Developments went into liquidation in 2023, three years before the trial concluded. Ordinarily, pursuing compensation against a company that no longer has assets or is no longer trading can be difficult.

    This is where the Employers’ Liability Tracing Office, or ELTO, becomes important.

    Archive of historic employers’ liability policies being traced to an insurer

    Established in 2011, ELTO maintains records of more than 40 million employers’ liability policies spanning more than a century. Its purpose is to help claimants and their legal representatives identify the insurer that covered an employer during the relevant period.

    The employer may have changed its name, merged, ceased trading or entered liquidation. Provided valid employers’ liability cover was in place at the time of the incident, a claimant may still be able to pursue the relevant insurer through the civil claims process, subject to the law, policy terms and available limits.

    ELTO does not pay compensation itself. It helps identify the insurer. The claim must still be established through the normal legal process.

    This is why accurate insurance records matter from the first day of trading. Contractors should retain employers’ liability certificates and schedules for at least 40 years as a sensible long-term record, particularly because occupational disease and some injury claims can arise many years after the employment period.

    Keep records of:

    • The exact legal name of the insured business
    • Previous trading names and company names
    • Subsidiaries and associated companies
    • Employers’ reference numbers and PAYE details
    • Policy numbers, insurers and renewal dates
    • Changes following incorporation, restructuring or acquisition

    The name on the policy should match the entity actually employing the workers. A trading name alone is not always enough.

    Why excavation risk is closely watched by insurers

    Construction remains the UK industry with the highest number of fatal workplace injuries. HSE’s latest figures record 25 construction worker deaths in 2025/26, with a fatal injury rate around 4.8 times the all-industry average.

    Across all industries, 18 fatalities in the same period involved people being trapped by something collapsing or overturning. That category includes trench and excavation failures. It is smaller than the category covering falls from height, but it remains a recurring cause of serious injury and death.

    For groundworks and demolition firms, trenching is not an occasional risk that can be dealt with through a generic method statement. Ground conditions change, water enters excavations, plant creates vibration and spoil placed too close to an edge can increase pressure on the trench sides.

    Underwriters looking at Construction Contractor Insurance will want to understand how the risk is controlled in practice, not only whether the paperwork exists.

    Practical steps for groundworks and demolition contractors

    At a minimum, contractors should review whether they have:

    • Competent temporary works design and supervision
    • Suitable trench support, battering or benching
    • Edge protection and properly controlled access
    • Daily excavation inspections, with findings recorded
    • Permit-to-work arrangements for higher-risk excavations
    • Exclusion zones around trench edges and operating plant
    • Ground condition surveys and checks for buried services
    • Controls for water ingress, vibration and nearby structures
    • Adequate supervision when work is under time or cost pressure
    • Clear responsibilities between principal contractors and subcontractors

    Groundworks safety checklist showing trench support, exclusion barriers and inspection controls

    Directors, contracts managers and site supervisors also need to understand that individual liability is real. The sentence given to Mr O’Connor demonstrates that safety duties are not limited to the corporate entity.

    From an insurance perspective, employers’ liability should be reviewed alongside public liability, contract works and plant cover. General Contractor Liability Insurance is often used as a broad description, but the individual sections of the policy matter. Public liability may respond to injury or damage suffered by members of the public or other third parties, while contract works and plant cover address different property and equipment exposures.

    Directors and managers should also ask whether D&O or management liability insurance can assist with defence costs in regulatory proceedings. This depends heavily on the wording. Defence costs may be covered in some circumstances, but fines remain uninsurable and exclusions may apply where conduct is deliberate, dishonest or reckless.

    At renewal, disclose enforcement notices, prosecutions and serious incidents accurately. Trying to minimise or omit a known prosecution can create a separate coverage problem and will usually make the underwriting conversation more difficult.

    For contractors looking for Business Insurance Essex, Business Insurance London or cover across Kent, the practical objective is not simply to find the cheapest premium. It is to make sure the policy reflects the work actually being carried out, the limits are adequate and the historic records can be traced if a claim arises years later.

    The practical conclusion

    The Banstead case should not be treated as just another headline about a large fine.

    It demonstrates that one serious site incident can create an uninsured criminal penalty, a potentially substantial civil compensation claim and a long-lasting underwriting and reputational record. Employers’ liability insurance cannot prevent unsafe work and cannot pay a criminal fine, but it can provide the financial protection intended for compensation claims involving employees.

    For businesses that later cease trading, ELTO may be critical in helping a bereaved family trace the insurer that stood behind the employer’s policy. That makes accurate policy records, correct insured names and proper disclosure more than an administrative task.

    The first priority remains preventing the incident. The second is making sure that, if the worst happens, the business, its people and those affected are not left without the right protection.

    Source: Insurance Business UK: “Trench death fines highlight where insurance can – and can’t – help construction firms”

    General information only. This article is not legal, health and safety or insurance advice. Contractors should obtain advice based on their own activities, policy wording and circumstances.

    Frequently asked questions

    Can criminal health and safety fines be covered by insurance?

    No. Criminal fines cannot generally be insured in the UK because doing so would undermine their deterrent purpose. A business must pay the fine itself.

    What does employers’ liability insurance cover?

    Employers’ liability insurance is designed to cover compensation claims and legal costs where an employee is injured, becomes ill or dies because of their work, subject to the policy wording, limits and exclusions.

    What happens to an employers’ liability claim if the company has gone into liquidation?

    A claimant may be able to identify the historic insurer through ELTO and pursue the civil claim against the relevant insurer, subject to the applicable legal process and policy terms.

    How much employers’ liability insurance must a UK contractor have?

    The statutory minimum is generally £5 million. Many employers’ liability policies provide £10 million, but contractors should review their contractual requirements, workforce, activities and potential claim values when selecting limits.

    Can D&O insurance pay a health and safety fine?

    No policy should be assumed to cover a criminal fine. Some D&O or management liability policies may provide defence costs for certain proceedings, but this depends on the wording and exclusions, particularly where deliberate or reckless conduct is alleged.

  • Nearly 100 Cases, £1.2bn in Dispute: The Cladding Litigation Wave Reaching Every Corner of Construction

    Nearly 100 Cases, £1.2bn in Dispute: The Cladding Litigation Wave Reaching Every Corner of Construction

    Almost 100 cladding, building and fire-safety cases are now active in London’s High Court, with a combined value of about £1.2bn, according to litigation intelligence platform Solomonic and reporting published by the Financial Times on 8 September 2026.

    That figure changes the way we should view the post-Grenfell building safety disputes. This is no longer a handful of headline judgments involving a small number of high-rise blocks. It is becoming a market-wide litigation wave, reaching developers, housebuilders, contractors, architects, façade engineers, specialist subcontractors, product manufacturers and social housing providers.

    The cases cover luxury developments, student accommodation, social housing portfolios and commercial buildings such as hotels. Many are proceeding under the Building Safety Act 2022, which has changed the potential routes to recovery and, in some cases, extended limitation periods for historic work.

    For construction businesses in Essex, Kent and London, the message is practical: work completed many years ago may still be relevant, and every link in the contractual chain needs to understand its exposure.

    Read the FT-syndicated report via Factinface.

    The chain reaction behind the £1.2bn

    The pattern appearing across many cases is familiar. A developer or building owner faces the cost of making a building safe, then brings a claim against the main contractor. The contractor in turn pursues the architect, façade engineer, specialist subcontractor or manufacturer. Those parties may then bring their own claims further down the supply chain.

    Andrew Parker, construction disputes and building safety partner at Forsters, described the dynamic plainly:

    “There are plenty of opportunities for people to point the finger or pass the buck. The contractor says I was working off the design from the architect, the architect says I spoke to the facade engineer, the facade engineer says I told the subcontractor what to do. And everyone says building control signed it off.”

    That is not simply a legal argument. It creates a large evidence problem. The court may need to understand who selected a product, who approved a design, what information was available at the time, what building control reviewed and whether the final installation matched the specification.

    The Mulalley v Sto judgment illustrates this chain clearly. A contractor that had settled with its client was able to pursue a cladding supplier and recover a substantial proportion of the relevant remediation costs. The court also allowed liability to reach the supplier’s overseas parent through a Building Liability Order.

    The wider point is that being the main contractor does not necessarily mean carrying the entire loss, but recovery depends on contracts, records, expert evidence and insurance arrangements that remain effective.

    Hand-drawn illustration of a developer, contractor, architect, façade engineer, subcontractor and manufacturer linked around a residential building

    The Building Safety Act has widened the risk

    The Building Safety Act 2022 has changed the risk landscape in two important ways.

    First, Building Liability Orders can allow a court to extend certain building safety liabilities from one company to associated companies where it is just and equitable to do so. That can include parent companies, sister companies and, in suitable circumstances, overseas entities.

    Our article on Building Liability Orders and whole-company group exposure explains why a project company or insolvent subsidiary may no longer be the only company in the frame.

    Second, the Act has extended limitation periods for certain claims relating to defective dwellings, including a retrospective period of up to 30 years in qualifying circumstances. This means work completed in 2005, 2006 or 2008 may still be examined today.

    That is particularly relevant to businesses across the South East. Many Essex, Kent and London contractors, consultants and specialist trades worked on residential schemes during that period. Some businesses have changed ownership, merged, closed divisions or moved away from the type of work they performed at the time. Their historic records and insurance policies may still matter.

    Lawyers representing defendants have argued that claims concerning old projects can be difficult to defend fairly because records are missing and witnesses have retired. Those arguments are likely to remain part of the wider debate, but businesses should not wait for the law to settle before reviewing their own records.

    Eclipse Tower shows how complicated one claim can become

    The Eclipse Tower dispute in Bristol is a useful example of the multi-party litigation now reaching the High Court.

    The 18-storey residential building sits above Harvey Nichols. After the Grenfell fire, inspections identified combustible materials within the external wall construction. The developer, Bristol Alliance, paid main contractor Sir Robert McAlpine £19m for remedial works but reserved its right to pursue recovery.

    Bristol Alliance sued McAlpine in 2023. McAlpine then brought claims against architect Benoy and subcontractor Richardson Roofing. Benoy pursued subconsultant Arup Façade Engineering, while Richardson Roofing brought insulation manufacturer Kingspan into the dispute, alleging it had been misled by product marketing.

    The High Court has ordered a major multi-party trial for next year.

    This is the “pass the buck” structure in practical form. Each party may have a different explanation of what happened, but all parties face legal costs, management time, expert evidence and the possibility of an adverse judgment.

    For contractors operating on thin margins, that cost can be severe even before liability is finally determined. A lengthy dispute can restrict borrowing, delay investment and put pressure on payment to subcontractors. In some cases, an adverse judgment combined with legal costs could push a business into insolvency.

    Ardmore and the danger of insolvency

    The Crest Nicholson v Ardmore dispute demonstrates how building safety litigation and insolvency can interact.

    Ardmore's main contracting businesses collapsed in 2026, and the company entered administration reportedly shortly before an adjudicator ordered payment of approximately £15m in connection with fire-safety defects at Admiralty Quarter in Portsmouth. Crest then used Building Safety Act provisions to pursue wider group entities connected to the contractor.

    The High Court sided with Crest in April, although the associated entities are appealing. Anthony Field of Rosenblatt warned that, unless the judgment is overturned or Parliament intervenes, the consequences could be devastating for the construction industry and could lead to more businesses entering insolvency.

    The financial impact does not stop with the defendant. As explained in our Ardmore subcontractor lesson, administration can leave subcontractors with unpaid applications, lost retentions, committed labour costs and little prospect of recovering what they are owed.

    Historic work and insurance need attention

    The Taylor Wimpey v Taylor Woodrow and Vinci Construction dispute concerns Victoria Wharf in Cardiff, with seven apartment blocks completed between 2005 and 2008 and approximately £30m in dispute. Under the former limitation rules, the right to sue would have expired. The extended limitation period has brought the historic project back into focus.

    The same issue may affect contractors and consultants that worked on residential developments throughout Essex, Kent and London. The fact that a project was completed, signed off or commercially closed does not necessarily mean the risk has disappeared.

    Businesses should review:

    • Retroactive dates on professional indemnity policies.
    • Run-off arrangements following a sale, closure or change of trade.
    • Notification obligations for circumstances that may give rise to a claim.
    • Whether historic work is properly described to insurers.
    • Products liability cover for supplied or specified materials.
    • Contractual rights of recovery against designers, suppliers and subcontractors.
    • Whether defence costs are covered when a contractor is caught between a client claim and a supply-chain recovery claim.
    • The effect of exclusions for defective work, contractual liability or known circumstances.

    A standard liability policy is not a universal answer to a building safety dispute. A contractor may need public liability, products liability and professional indemnity cover, and the policy wording will determine how those covers respond.

    This is why the PI exposure hiding in construction contracts deserves attention. Design coordination, specification and fitness-for-purpose obligations can create professional indemnity exposure even where a business still describes itself as “just the contractor”.

    Hand-drawn illustration of a historic residential tower, archived project records, a 30-year timeline and an insurance shield

    What contractors should do now

    I recommend that contractors and specialist firms take eight practical steps:

    1. Identify historic residential and fire-safety-related projects. Include work carried out between 2005 and 2016, not only recent developments.
    2. Preserve records. Retain contracts, drawings, specifications, product literature, inspection reports, certificates, correspondence and settlement documents.
    3. Review limitation exposure. Take legal advice on whether the Building Safety Act or another route could bring an old project back into scope.
    4. Audit insurance programmes. Check retroactive dates, run-off cover, limits, exclusions and notification clauses.
    5. Notify potential circumstances promptly. A letter of claim, adjudication notice, investigation or request for historic project information may require notification.
    6. Map the contract chain. Identify who owes an indemnity or contribution if your business is pursued for a product, design or installation you relied on.
    7. Check group-company exposure. Understand which parent, subsidiary or associated companies may be relevant to a Building Liability Order.
    8. Monitor insolvency risk. Review the financial position of major clients, contractors and supply-chain partners before exposure becomes too large.

    The estimated total cost of fixing unsafe blocks is between £12.6bn and £22.4bn, according to a parliamentary report cited in the recent reporting. Only a small number of judgments have been handed down so far, so the ultimate question of who pays remains unresolved.

    Simon Tolson of Fenwick Elliott has said that the Building Safety Act is reshaping liability across the construction sector. I think that is the right description. The law is not simply creating new claims; it is changing how businesses assess corporate structure, historic work, contracts and insurance.

    At Moyak Insurance Services, we help businesses review Construction Contractor Insurance, General Contractor Liability Insurance, professional indemnity and wider Business Insurance Essex and Business Insurance London requirements. The objective is not just to find a policy, but to understand whether the programme reflects the work your business has done, the contracts it is accepting and the risks still sitting in its past.

    The construction industry is trying to resolve a 40-year problem in a few years. As Andrew Parker observed, far-reaching measures such as 30-year limitation periods and piercing the corporate veil have arrived quickly. Contractors should respond just as quickly by reviewing their records, contracts and insurance before the next letter arrives.

    This article is for general information only and is not legal advice. Building Safety Act claims, limitation issues, Building Liability Orders and insurance coverage depend on the facts, applicable law and policy wording. Obtain specialist legal advice and speak to your insurance broker about your circumstances.

    Frequently asked questions

    How many cladding and fire-safety cases are active in the High Court?

    Nearly 100 cases are active in London’s High Court, according to reporting by the Financial Times on 8 September 2026 based on data from Solomonic. The combined value is reported to be about £1.2bn.

    Can old construction projects still be pursued?

    Potentially, yes. The Building Safety Act has retrospectively extended certain limitation periods for qualifying claims relating to defective dwellings, in some cases up to 30 years. The applicable legal route and facts must be assessed by a solicitor.

    Can a Building Liability Order reach a parent company?

    It can. A Building Liability Order may extend certain building safety liabilities to associated companies where the statutory conditions are met and the court considers the outcome just and equitable. It is not automatic.

    What insurance should a construction contractor review?

    A contractor should consider Construction Contractor Insurance, public and General Contractor Liability Insurance, products liability, professional indemnity, employers’ liability, contract works, run-off and any project-specific arrangements. The correct cover depends on the work and contractual obligations.

    Should a contractor notify insurers about a historic building-safety concern?

    A potential claim or circumstance may need to be notified promptly, particularly under a claims-made professional indemnity policy. Contractors should review the policy wording and obtain advice rather than waiting for a formal court claim.

    Why do contract chains matter in cladding disputes?

    The developer may pursue the main contractor, which may then seek contributions from architects, façade engineers, subcontractors or manufacturers. Clear contracts, preserved records and enforceable insurance obligations can affect whether a business is able to recover its losses.